Hot payrolls put a December Fed hike in play going into CPI week
A payrolls beat took December Fed hike odds to about 77% to 80%, and Tuesday's CPI is the last print before the meeting. AI earnings from CoreWeave and Applied Materials follow a 6.5% Nasdaq 100 drop
As always, this is not financial advice. This is a research piece, not investment guidance; always do your own research before trading.
Where the week starts?
Democrats win Congress, and payrolls flip Fed pricing
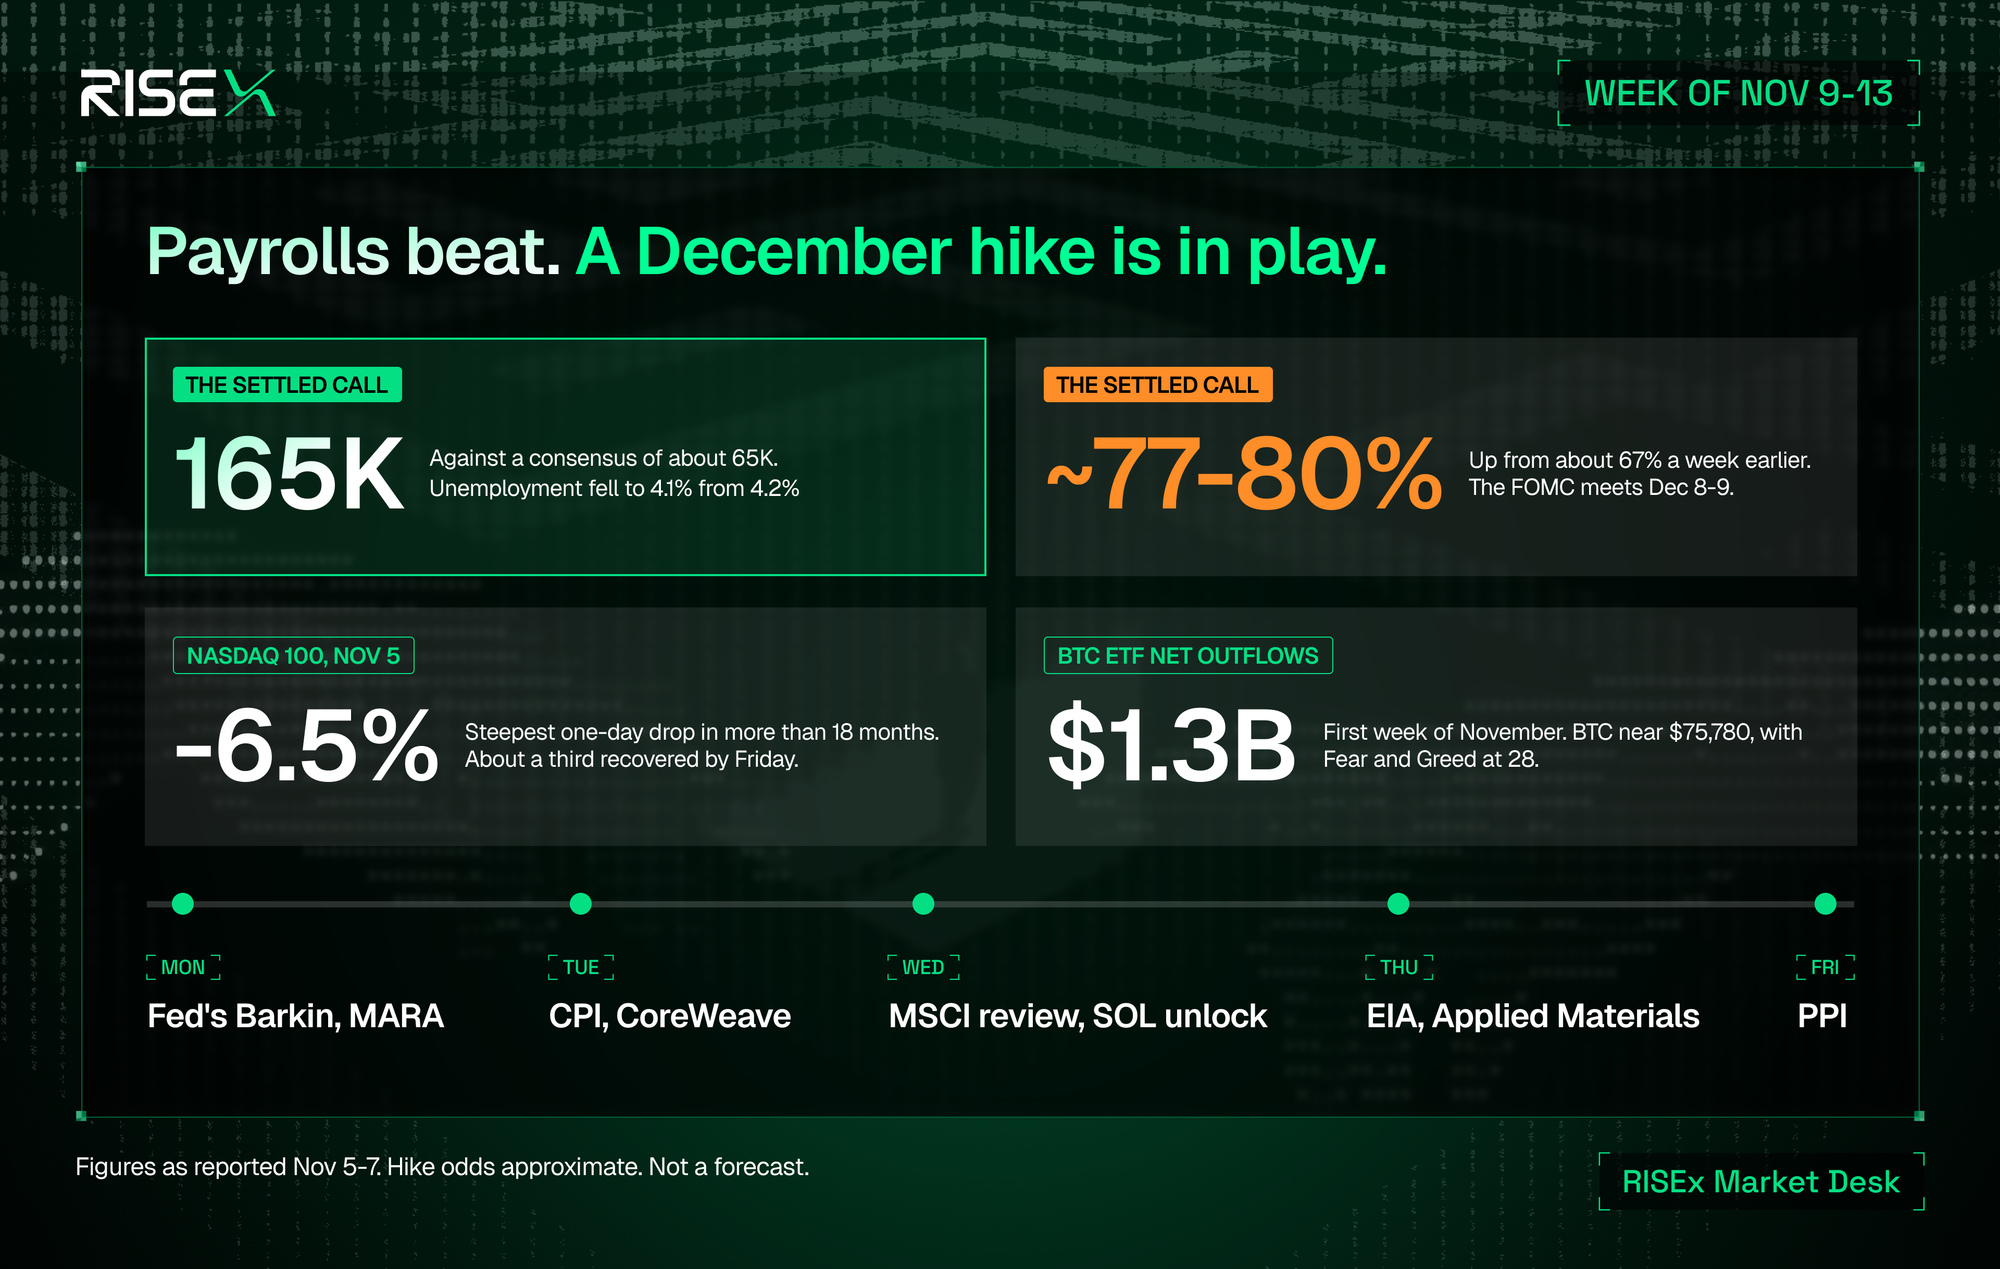
Democrats secured full control of Congress in the November 3 midterms, flipping the Senate, just as ACM reported. October payrolls surged by 165,000 against the expectations of roughly 65,000, and unemployment ticked down to 4.1% from 4.2%.
CME data now puts the odds of a 25bp hike at the Dec. 8-9 FOMC meeting at roughly 78%-80%, up from about 67% last month.
With the midterms decided, the spotlight shifts to jobs reports and now the key driver of rate expectations.
CPI Tuesday is the last read before the FOMC
October CPI drops Tuesday at 8:30 am ET (13:30 UTC). One consensus estimate puts headline CPI at +0.3% m/m and 3.7% y/y, with core at +0.2% m/m and 2.6% y/y. The week’s first Fed voice is Richmond Fed President Tom Barkin, speaking Monday at 12:15 pm ET. PPI follows Friday at 8:30 am ET; no consensus estimate was available.
Hot CPI prints have rocked markets before. On September 13, 2022, August CPI came in at 8.3% vs. 8.1% expected, sending the Dow down 1,276 points (-3.94%), its worst day since June 2020 as investors repriced for a steeper rate path.
CPI doesn’t have to be dramatic to move equities; it just has to be different from consensus. With roughly 77%-80% already priced for December, a surprise in either direction will be the bigger risk than an in-line number.
Gold rebounds and Brent posts its steepest weekly fall since 2020
Gold ended Friday at $4,045, up roughly 4% on the week after tagging a 13‑month low. Silver closed at $51.89, up 5.75%. On RISEx, XAU was traded at $4,069.45 and XAG at $52.0196.
Brent settled at $98.32 and WTI at $90.83, marking Brent’s steepest weekly drop since 2020 after reports that Iran sent a nuclear proposal via Qatar. Despite that, three more tanker attacks were reportedly recorded in the Strait of Hormuz on Thursday. On RISEx, CL trades at $90.592 and BZ at $97.597.
Metals bounced from last week’s lows even as rate-hike odds climbed. Oil took its cue from the Iran proposal headlines, largely shrugging off the tanker-attack reports. This week’s key scheduled oil catalysts include the EIA Short‑Term Energy Outlook (Tuesday) and the delayed weekly inventories (Thursday).
AI earnings test the rebound after a 6.5% Nasdaq 100 drop
The Nasdaq 100 sank 6.5% on November 5, its sharpest one-day drop in more than 18 months, then recovered about a third of that loss by Friday. The next catalyst is CoreWeave on Tuesday at 5:00 pm ET (consensus EPS -$1.45 vs. -$0.31 a year ago). Applied Materials reports Thursday at 4:30 pm ET, alongside Nebius, Cerebras, and Cisco. MARA Holdings reports Monday after the close.
On RISEx, CRWV was traded at $46.38, SKHYNIX at $873.98, MU at $696.25 and NVDA at $187.56.
CoreWeave is the first real check on whether Friday’s rebound has legs, coming just five days after the selloff. Applied Materials hits Thursday evening right ahead of the Seoul open Friday, making it the key equipment and memory capex read-through for SK Hynix.
Bitcoin sits in fear while ETFs bleed and Binance recovers
BTC hovered near $75,780 on November 7, down 2.2% on the week, as the Fear & Greed Index sat at 28. U.S. spot bitcoin ETFs saw roughly $1.3B in net outflows in the first week of November, led by IBIT at about $1.2B.
On RISEx, BTC was traded at $75,989.40 and ETH at $2,237.52.
Binance’s recovery from its $6.3B hack, disclosed Oct. 29, is still underway. The exchange said Wednesday it has replenished about 98% of the affected funds, up from roughly 95% on Monday. The remainder sits in less liquid tokens Binance says it’s repurchasing via market and OTC buys. Its proof-of-reserves snapshot now spans 44 cryptocurrencies, up from 10, with a full zero-knowledge proof expected to take 50–60 hours. Withdrawals resumed in phases starting November 1, though no source has confirmed which networks, if any, remain suspended.
Bitcoin goes into CPI week in the red, with ETF outflows adding pressure. Binance’s recovery numbers are self-reported; next up is the full proof-of-reserves release, which is the key checkpoint to verify.
Strategy's MSCI review and a Solana unlock
MSCI publishes its November index review results on Wednesday evening. New rules screening out non-operating holding companies put Strategy at risk of a later exclusion, with an estimated 3% to 4% of its shares held in MSCI-tracking funds. Any removal would take effect after the close on November 30, not this week. MSTR trades at $128.45 on RISEx.
Solana's monthly stake-lock unlock lands Wednesday, about 204,000 SOL, or roughly $18.3M and 0.035% of supply. SOL was traded at $89.508 on RISEx.
The MSCI announcement can move MSTR on Wednesday night even though any exclusion would come later. The Solana unlock is small against supply.
The week, day by day
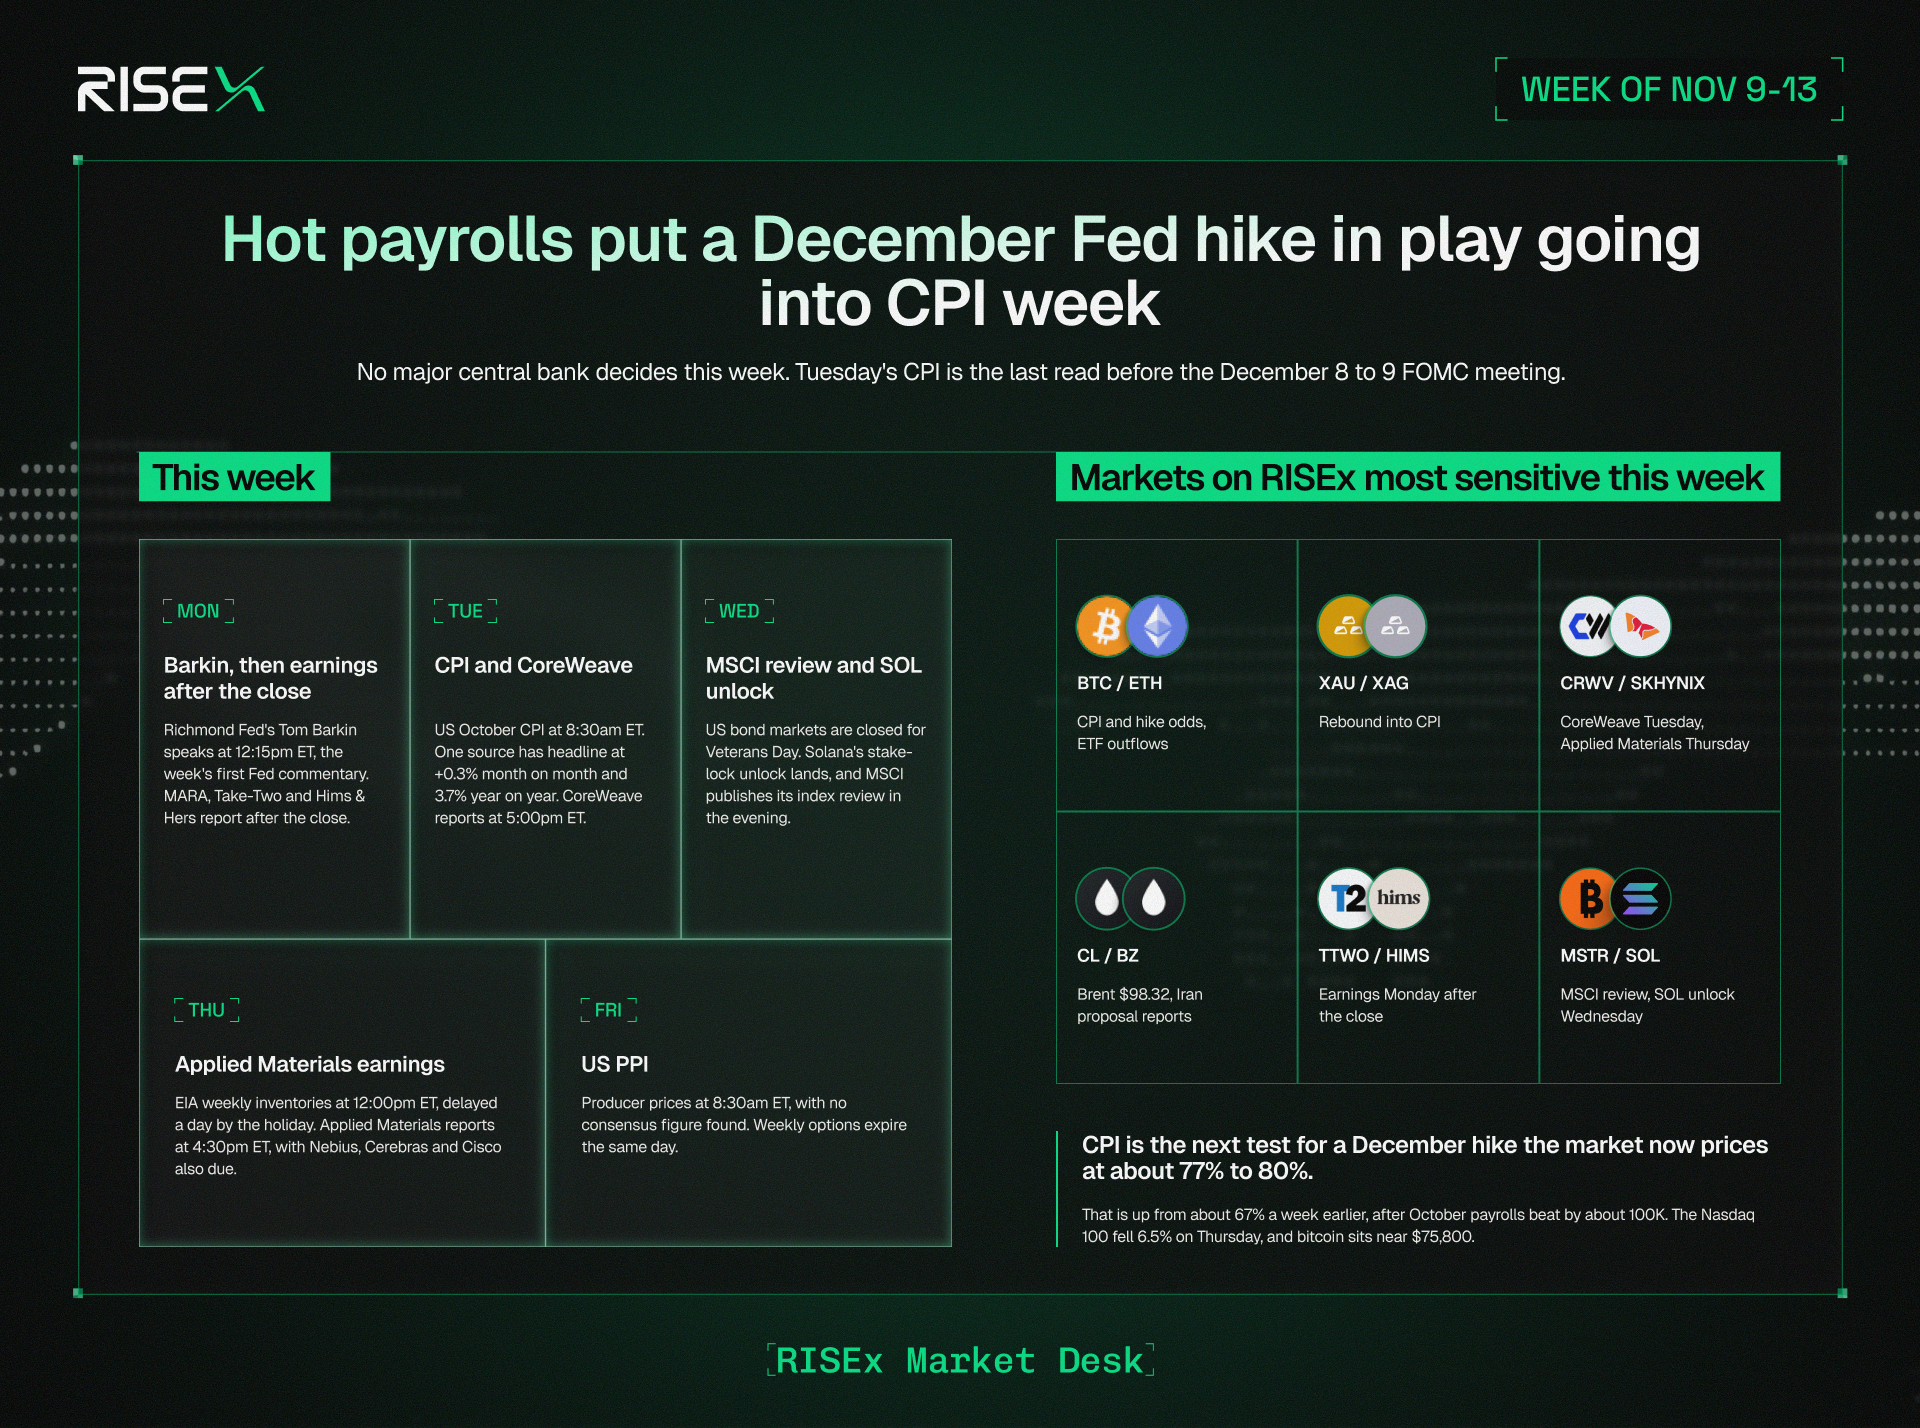
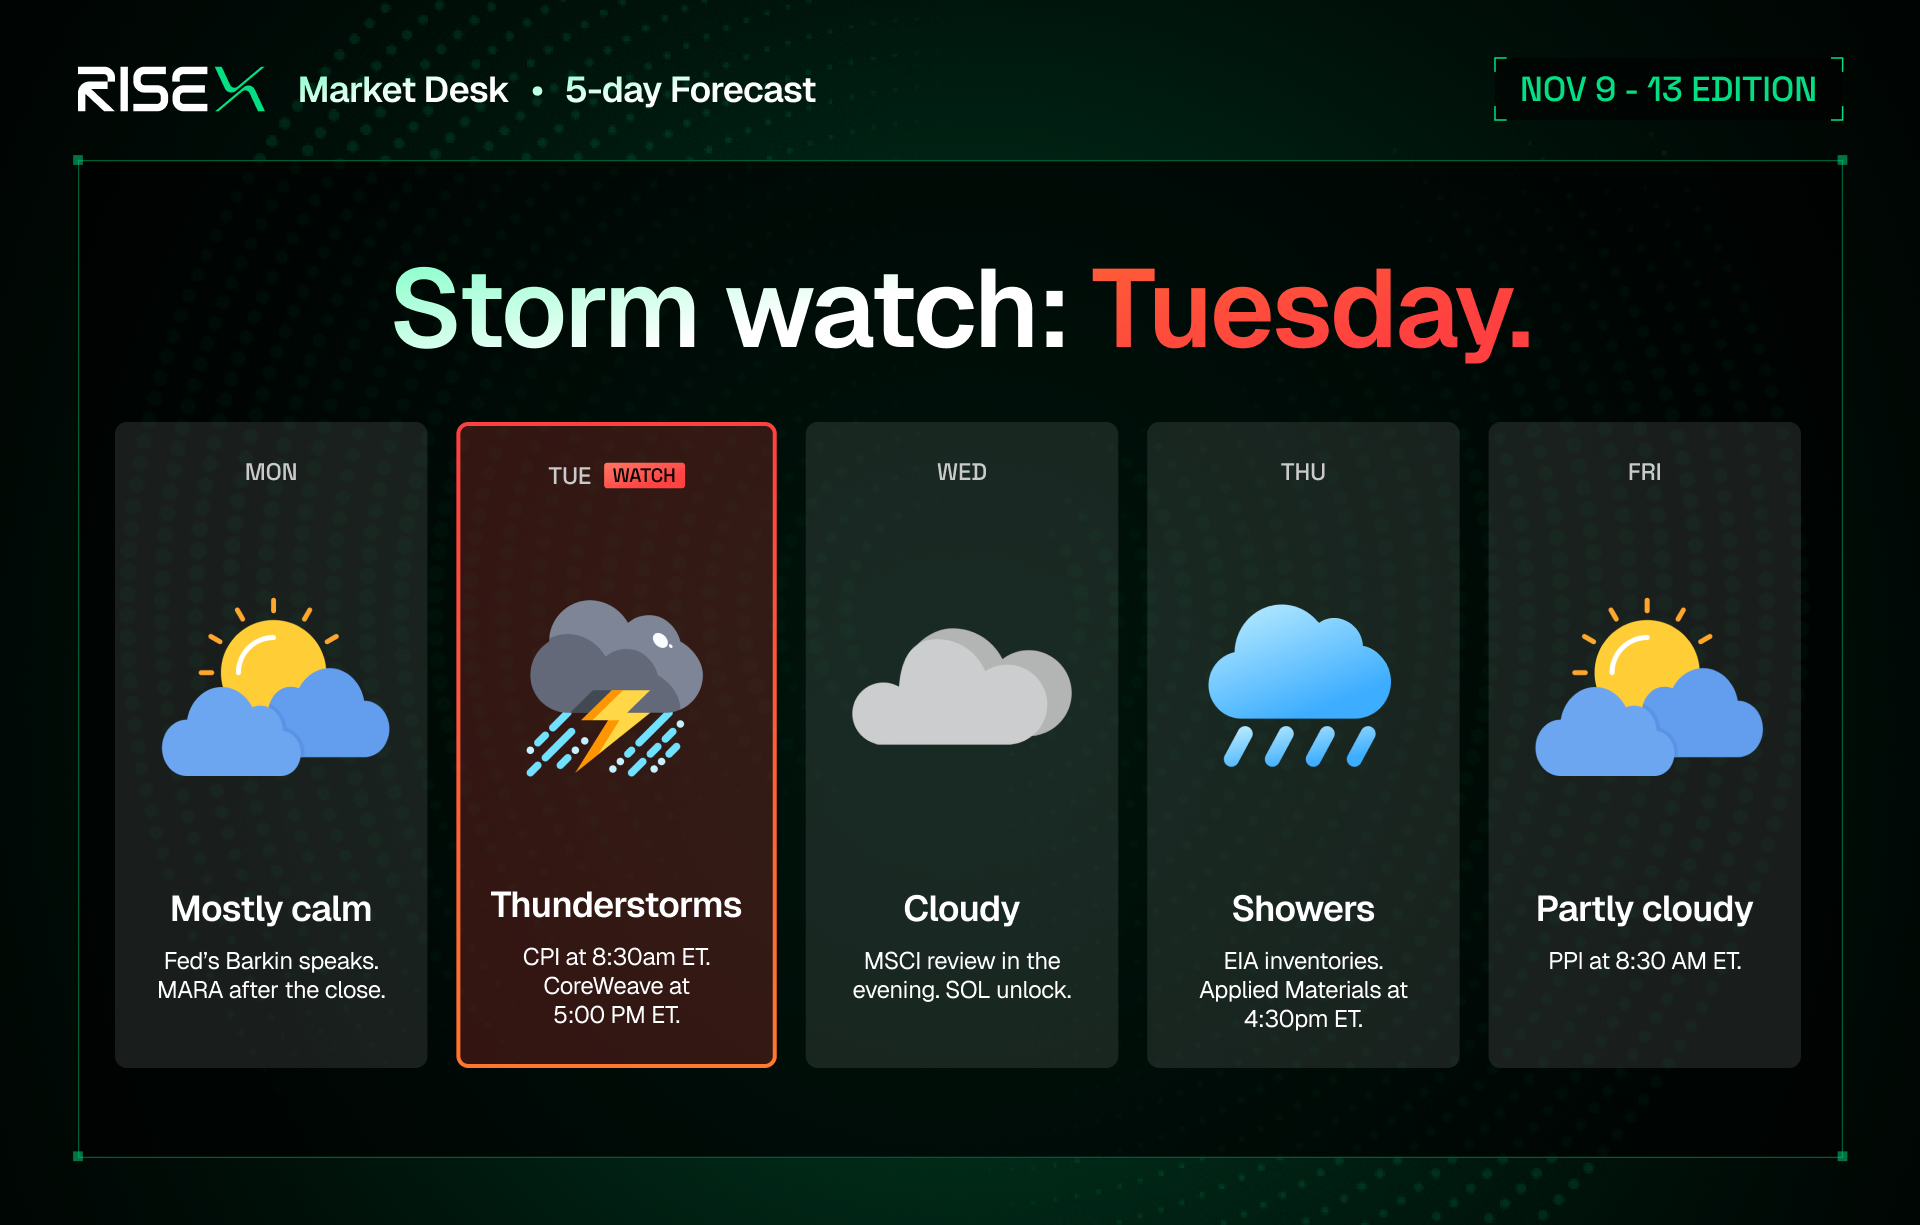
- Monday, November 9: Richmond Fed's Barkin at 12:15pm ET, then earnings after the close from MARA, Take-Two and Hims & Hers.
- Tuesday, November 10: US October CPI at 8:30am ET, EIA Short-Term Energy Outlook at 12:00pm ET and CoreWeave earnings at 5:00pm ET.
- Wednesday, November 11: US bond markets closed for Veterans Day, with equities and crypto trading normally, the Solana unlock and MSCI's review results in the evening.
- Thursday, November 12: EIA weekly inventories at 12:00pm ET, delayed a day by the holiday, and Applied Materials at 4:30pm ET.
- Friday, November 13: US October PPI at 8:30am ET and the standard weekly options expiry.
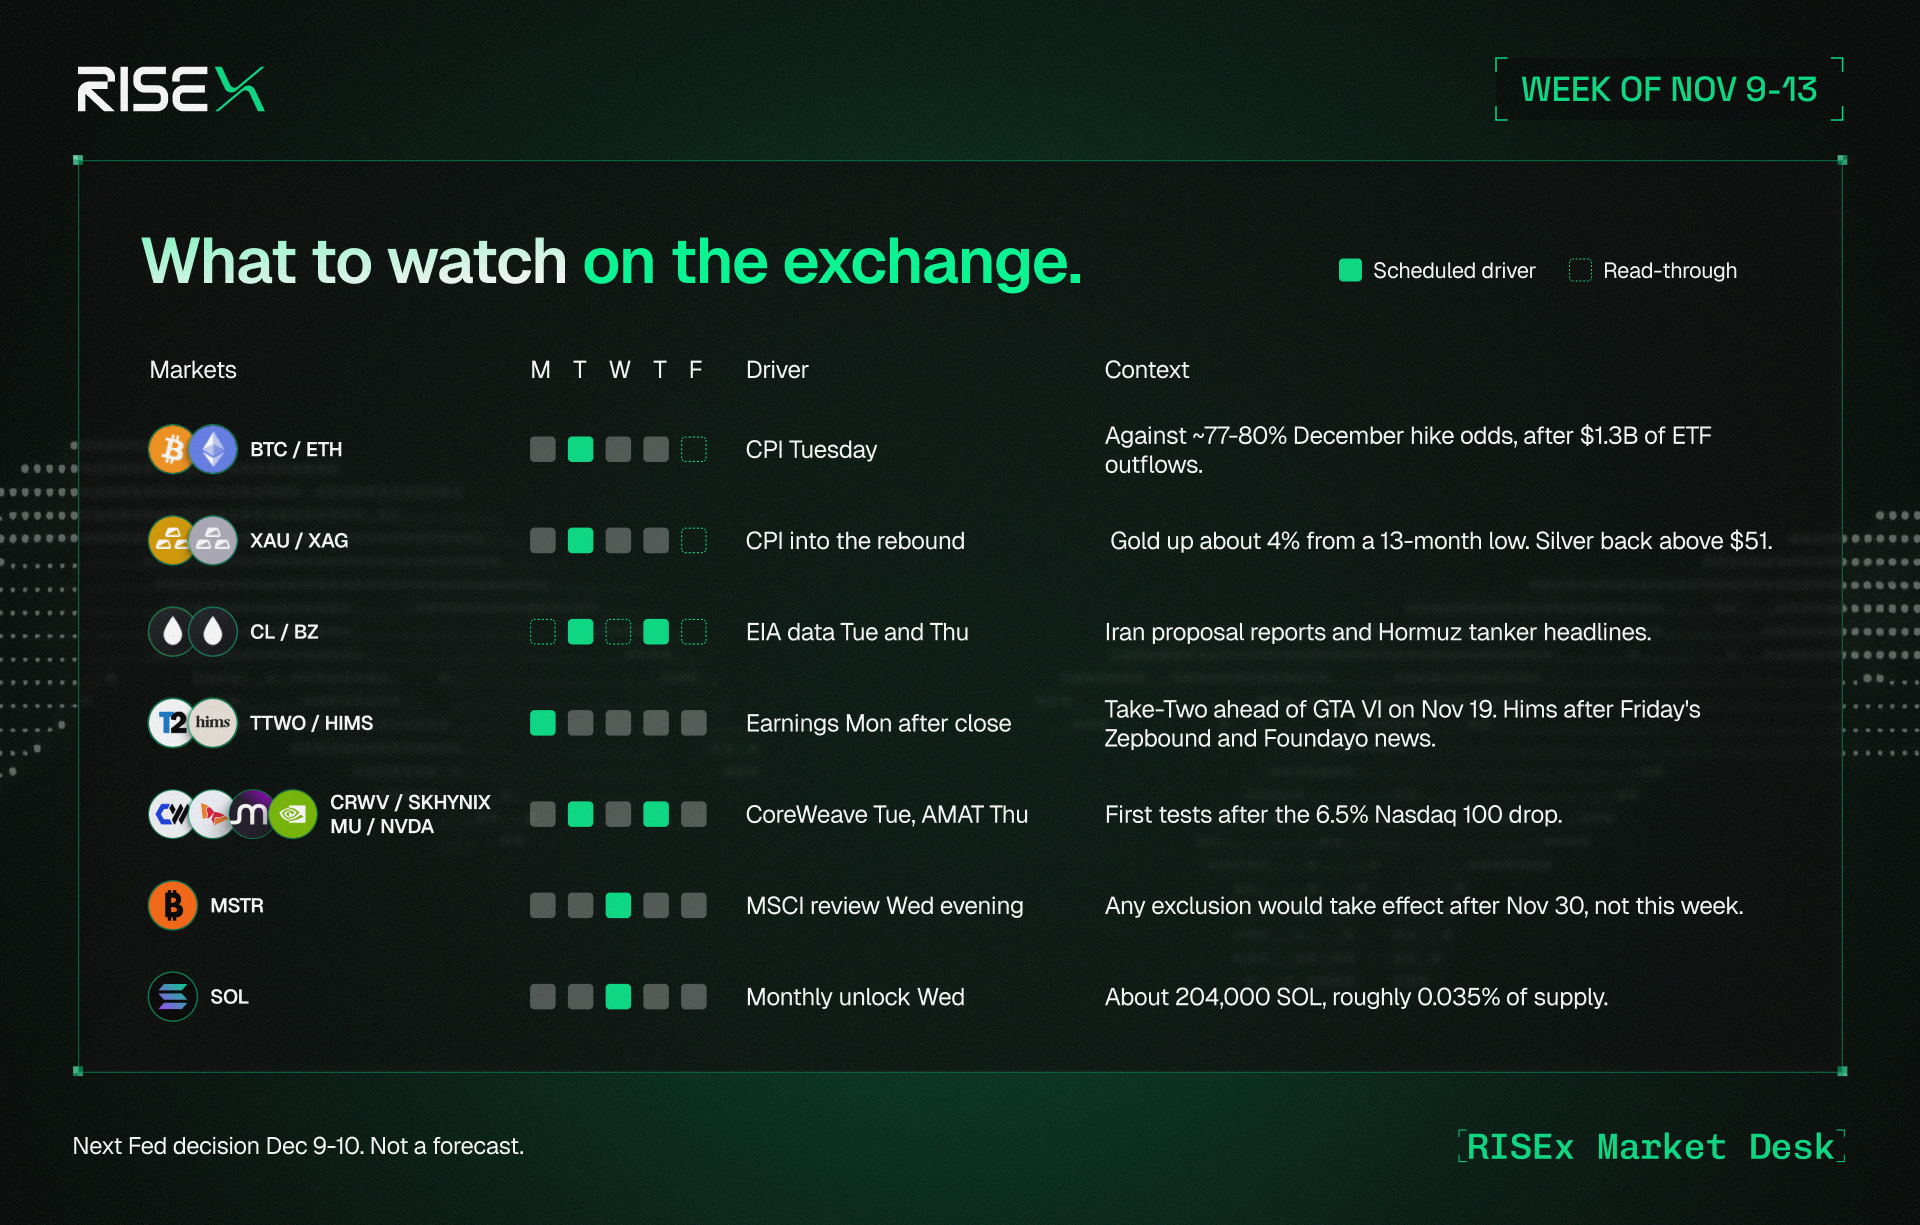
What to watch on the exchange
FAQ
When is the October CPI report?
Tuesday, November 10 at 8:30am ET (13:30 UTC).
What is expected for October CPI?
One sourced consensus has headline at +0.3% month on month and 3.7% year on year, and core at +0.2% and 2.6%.
Is a Fed rate hike expected in December?
The odds of a 25bp hike at the December 8 to 9 meeting at roughly 77% to 80%, up from about 67% a week earlier.
Is there a central bank decision this week?
No Fed, ECB, BoJ or RBA decision is scheduled for November 9 to 13. The next listed items are the FOMC Minutes on November 18 and a PBoC rate setting on November 19.
How did October payrolls come in?
165,000 against a consensus of roughly 65,000, with unemployment at 4.1%.
Who won the US midterms?
Democrats won full control of Congress, flipping the Senate.
Why did oil fall last week?
Brent's steepest weekly fall since 2020 links to reports that Iran sent a nuclear proposal through Qatar. Brent settled Friday at $98.32.