The RBA looks set to hike, and Friday's payrolls decide the Fed's October move
Two weeks after the Fed's first hike since 2023, the Reserve Bank of Australia looks set to become the third major central bank to tighten policy in barely a month. It shares the calendar with the most consequential US jobs report since the Fed's pivot.
As always, this is not financial advice. This is a research piece, not investment guidance; always do your own research before trading.
The RBA is next
The Fed raised the federal funds target range by 25bps to 3.75% to 4.00% on September 16. It was the first hike since 2023 and the first under Chair Kevin Warsh. The Bank of Japan's hike took effect September 24 and lifted its policy rate to roughly 1.25%.
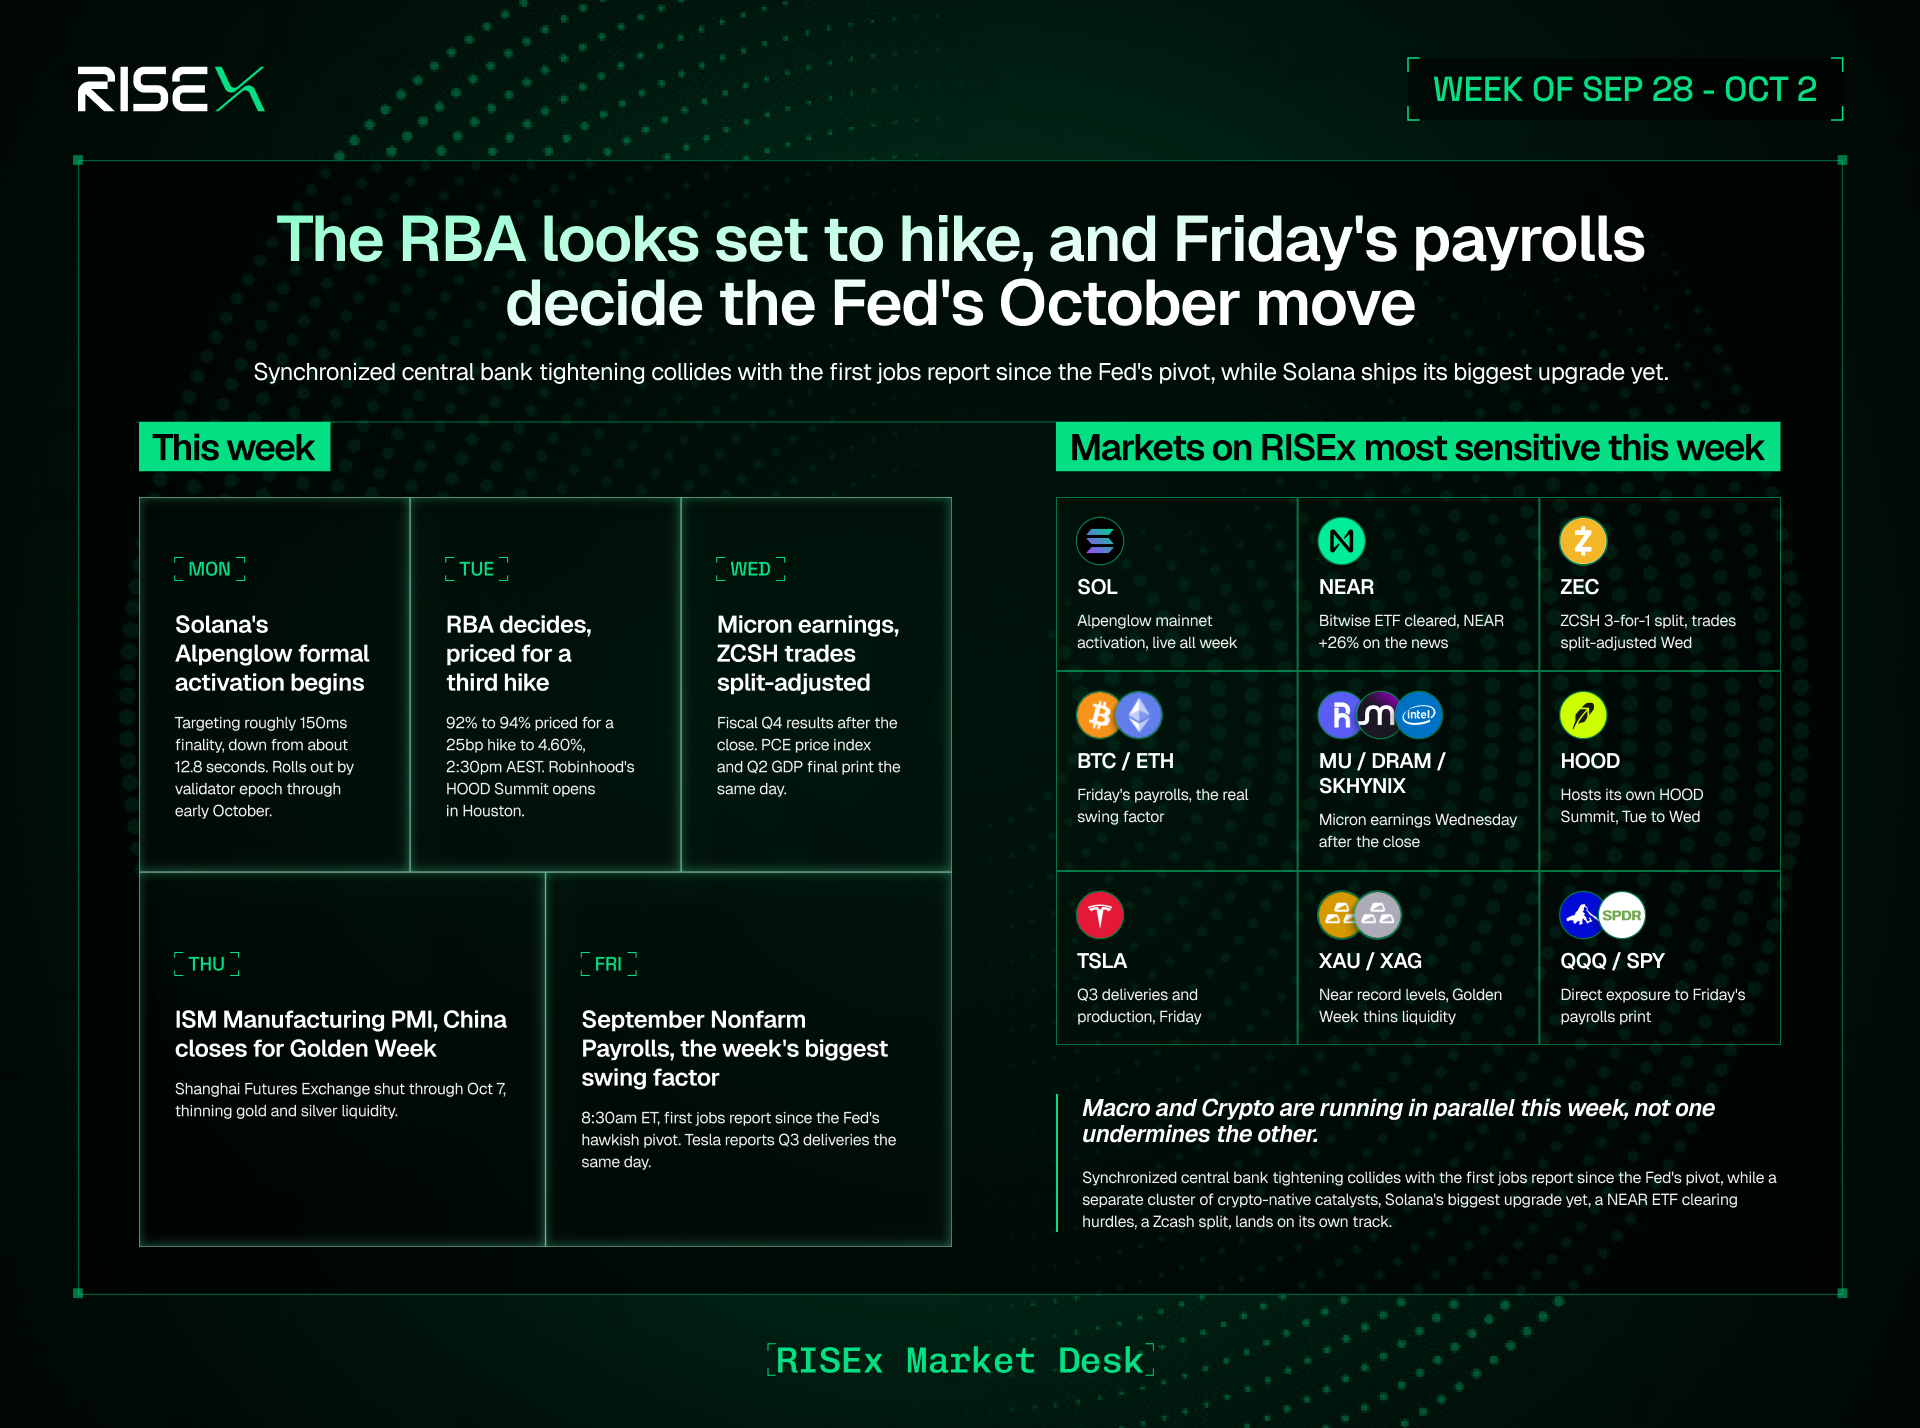
The RBA meets Tuesday, September 29, at 2:30pm AEST. Markets price a 92% to 94% chance of a 25bp hike to 4.60%, with trimmed mean inflation stuck at 3.6% y/y. If the RBA hikes, three major central banks will have tightened within two weeks of each other, all facing the same inflation problem.
Friday's payrolls decide October
The Fed's next move is still open. On September 17, markets had the October meeting close to a coin flip. Polymarket showed about 52% hold and 48% hike, and CME FedWatch showed about 42% hold and 51% hike. Around 88.5% of traders expected at least one more hike by the December 9 meeting. By September 23, October hike odds had climbed further. Fed Governor Michael Barr had said more tightening looked "likely," and PCE inflation was still running hot, at 3.7% y/y headline and 3.3% core.
September Nonfarm Payrolls print Friday at 8:30am ET. A strong number makes an October hike more likely. A weak one reopens the case for waiting until December. JOLTS on Tuesday, PCE and final Q2 GDP on Wednesday, and ISM Manufacturing on Thursday all bear on the same question. Payrolls is the number the market will actually trade.
A government shutdown is off the table this week. Congress passed a continuing resolution, which Trump signed on September 2, funding the government through December 11.
Solana starts Alpenglow
Alpenglow, Solana's new consensus protocol, begins its formal activation path on Monday, September 28. It targets finality of about 150ms, down from roughly 12.8 seconds today, and rolls out by validator epoch through early October. It is the largest consensus change the network has shipped.
Two other crypto catalysts land the same week. Bitwise's spot NEAR ETF (ticker NRR) cleared NYSE Arca and SEC hurdles, according to September 24 reporting, and NEAR rose roughly 26% on the news. Grayscale's Zcash trust (ZCSH) completes a 3 for 1 share split this week. The record date is Monday's close, new shares go out Tuesday, and split adjusted trading starts Wednesday. The trust has taken in more than $233M since it launched on August 25.
Equities
Micron reports fiscal Q4 results Wednesday, September 30, after the close. Its guidance has usually moved the stock more than the headline numbers. Robinhood holds HOOD Summit '26 in Houston on Tuesday and Wednesday and is expected to announce updates to its active trader tools and tokenized assets. Tesla reports Q3 deliveries and production on Friday, October 2. No time has been announced.
The week, day by day
- Monday, September 28: Alpenglow activation begins. The record date for the ZCSH split is at the close. No major macro data.
- Tuesday, September 29: The RBA decides at 2:30pm AEST, with markets pricing a 92% to 94% chance of a 25bp hike to 4.60%. US JOLTS data also comes out. New ZCSH shares are distributed. HOOD Summit opens in Houston.
- Wednesday, September 30: PCE and final Q2 GDP print. Micron reports after the close. ZCSH starts trading split adjusted. HOOD Summit day two.
- Thursday, October 1: ISM Manufacturing PMI. Mainland Chinese markets, including the Shanghai Futures Exchange, close for Golden Week through October 7. That thins liquidity in gold, silver and industrial metals.
- Friday, October 2: September Nonfarm Payrolls print at 8:30am ET. Tesla reports Q3 deliveries and production. The weekly Deribit BTC and ETH options expiry settles at 08:00 UTC, about four and a half hours before payrolls. It is smaller than the roughly $16.6B quarterly expiry on September 25.
What to watch on the exchange
- SOL: the live catalyst of the week. Alpenglow's mainnet activation rolls out by validator epoch through early October, independent of anything on the macro calendar.
- NEAR: Bitwise's spot ETF cleared NYSE Arca and SEC hurdles, NEAR already up roughly 26% on the news heading into this week.
- ZEC: Grayscale's ZCSH executes its 3-for-1 split this week, split-adjusted trading starting Wednesday, following a genuine inflow surge rather than a purely mechanical event.
- BTC and ETH: Friday's Nonfarm Payrolls is the week's real swing factor for October-versus-December hike odds, landing on top of fading ETF inflow momentum from the prior week.
- MU, DRAM, SNDK, SKHYNIX: Micron's fiscal Q4 results land Wednesday after the close. Guidance, not the headline print, is what tends to move the memory-chip complex.
- HOOD: hosts its own catalyst, the HOOD Summit '26 in Houston, Tuesday through Wednesday.
- TSLA: Q3 deliveries and production land Friday, no set time confirmed.
- XAU and XAG: sit near record levels heading in, with China's Golden Week closure removing a major trading venue for the back half of the week.
- QQQ and SPY: direct exposure to Friday's payrolls print and to a third central bank joining the hiking cycle.
- CL and BZ: positioning likely starts drifting ahead of OPEC+'s October 4 meeting, against a backdrop of Strait of Hormuz disruption headlines.
FAQ
Why does the RBA decision matter?
A hike would make the RBA the third major central bank to tighten within two weeks, after the Fed on September 16 and the Bank of Japan on September 24. The decision is Tuesday, September 29, at 2:30pm AEST. Markets price a 92% to 94% chance of a 25bp hike to 4.60%, with trimmed mean inflation at 3.6% y/y.
Why is Friday's jobs report the biggest catalyst?
It is the first US payrolls report since the Fed turned hawkish. Pricing for the October 27 to 28 meeting has moved more hawkish since Governor Barr said on September 23 that more tightening looked "likely." Friday's report is the next hard data point that pricing will have to absorb.
What is Alpenglow?
It is a consensus upgrade that targets about 150ms finality, down from roughly 12.8 seconds. Activation begins Monday, September 28, and rolls out by validator epoch through early October.
What happened with the NEAR ETF?
Bitwise's spot NEAR ETF (NRR) cleared NYSE Arca and SEC hurdles, according to September 24 reporting, and NEAR rose about 26%. Its first trading day had not been confirmed when this piece was published.
What matters in Micron's earnings?
Micron reports fiscal Q4 results Wednesday, September 30, after the close. Guidance usually moves the stock more than the headline numbers. The read carries over to the other DRAM, NAND and HBM names listed on RISEx.
About RISEx
RISEx is the first enshrined on-chain CLOB, built directly into RISE, an Ethereum L2. In the first five months of its invite-only launch, RISEx has cleared over $10B in volume and reached a $68M peak in open interest, with more than 20,000 registered users. In July, RISEx launched Ignite, its rewards points program, which will run until Q2 2027.
About RISE
RISE is an EVM Layer 2 built for high-performance trading. It offers 1ms latency, 50k+ TPS, and 5 Gigagas/s of throughput, and it has been the most performant EVM chain since launch (rollup.wtf).
Official links
- Trade: https://rise.trade
- RISE Chain: https://risechain.com
- X (RISEx): /risextrade
- X (RISE): /risechain
- Discord: Join Discord Server