The Fed's blackout period, earnings and Friday's flash PMIs carry the week
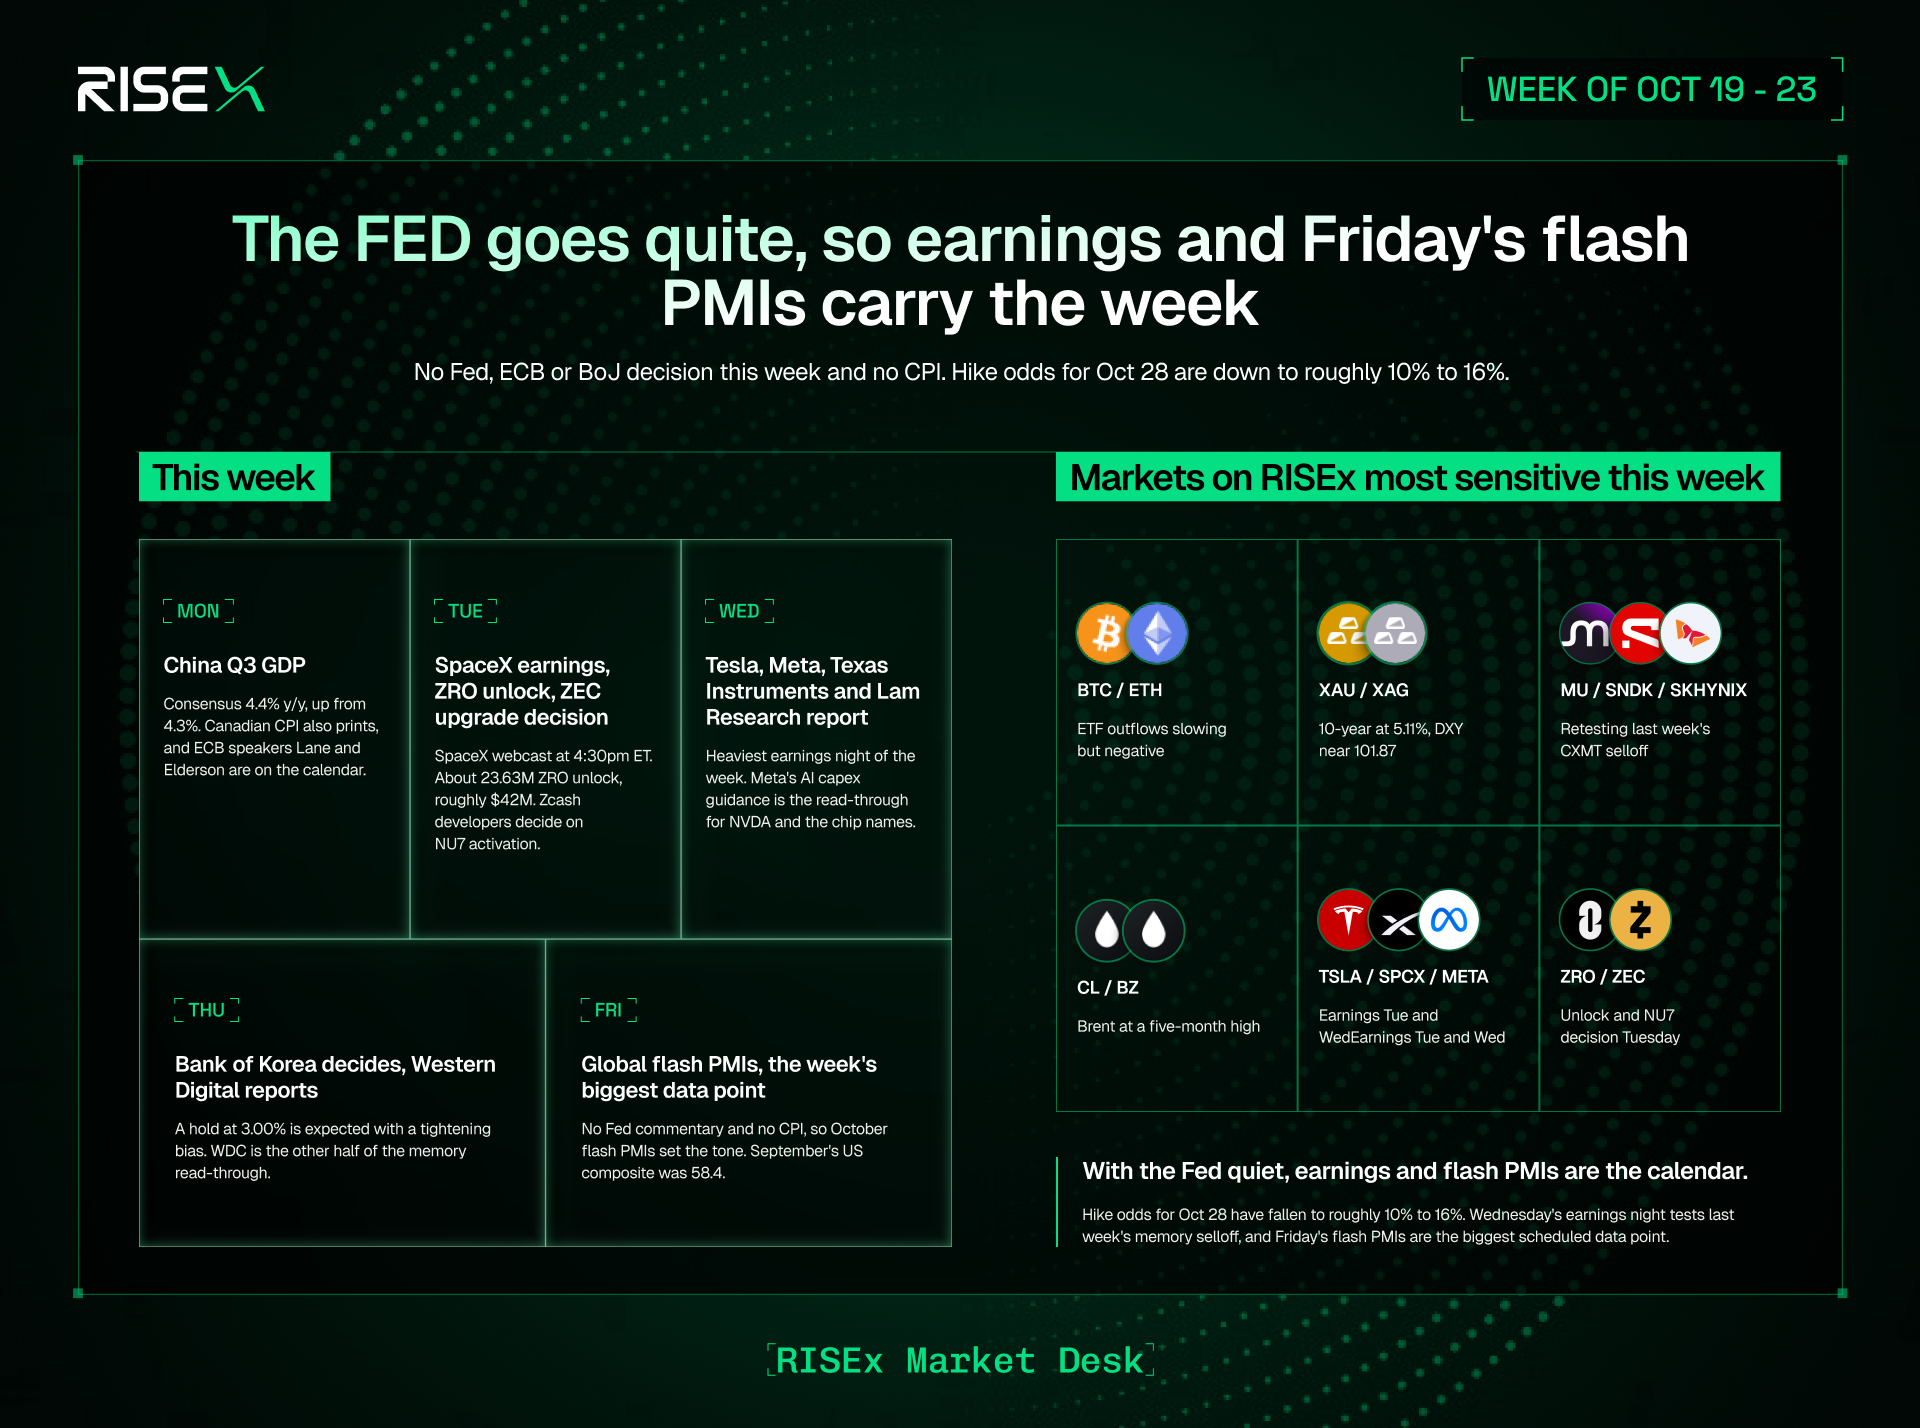
Fed officials have gone quiet ahead of the October 27 and 28 meeting, and pricing for an October hike has dropped to roughly 10% to 16%. With no rate decision and no CPI this week, earnings and Friday's flash PMIs have to carry the calendar.
As always, this is not financial advice. This is a research piece, not investment guidance; always do your own research before trading.
Fed entered blackout period
No Fed, ECB or BoJ rate decision falls inside this window. The FOMC meets October 27 and 28, with the ECB on October 28 and 29 and the BoJ on October 29 and 30, all the following week. The Fed has also stopped talking. Chair Kevin Warsh said on October 14 that the Fed is "not in that business" of hinting at policy ahead of time, after at least five officials had spent two weeks signaling no urgency to move, which means no scheduled Fed commentary all week.
Pricing has moved with it. Odds of a hike on October 28 have dropped to roughly 10% to 16%, down from 40% to 60% right after the hotter-than-expected September CPI report, while a December hike is priced near 89%. The target range has stood at 3.75% to 4.00% since the September 16 hike. Rates and the dollar are still elevated. The 10-year Treasury yield closed Friday at 5.11% and the dollar index near 101.87.
Oil is the loudest macro line
Brent settled at $109.86 on Thursday, October 16, its highest since May, up 3.7% on the day and 4.9% on the week, on Houthi strikes on Saudi Arabia, Ukrainian strikes on Russian refineries and a US offer of up to 17M barrels from the Strategic Petroleum Reserve. Crude is up more than 75% year to date. CL traded at $99.06 and BZ at $107.04 on RISEx, off the Thursday peak but still elevated.
Pressures on last week's memory selloff
One supply-chain headline did all the damage in chips last week. Reports that China’s CXMT is pushing toward a 4F2 DRAM design sparked a broad derating: SK hynix fell approx 18%, SanDisk 15%, and Micron 13% in the week to Oct. 16, even as Goldman Sachs argued the panic was overdone.
This week is the real-time verdict: does that move stick, or snap back? Texas Instruments and Lam Research report Wednesday night alongside Tesla and Meta. On Thursday, Western Digital - SanDisk’s former parent, prints fiscal Q1 2027, with the call at 4:30pm ET. Lam is the cleanest read on chip equipment; Western Digital is the storage check.
Thursday also adds a Korea macro layer: SKHYNIX and KORU trade into the Bank of Korea rate decision. The base case is a hold at 3.00%, a third straight pause after back-to-back 25bp hikes in July and August while the board is expected to lean hawkish.
Meta is the other semiconductor tell, via a different channel. It reports Q3 at 4:01 pm ET and the call at 4:30pm ET, and its AI capex outlook is the most direct read-through for NVDA and the broader chip trade. Street revenue consensus is around $63.3B, though per-share estimates vary meaningfully by source.
Crypto side: Two catalysts and ETF flows
On this Tuesday, LayerZero will unlock roughly 23.63M ZRO, about 5.93% of circulating supply with 10.63M allocated to core contributors and 13M to strategic partners. That same day, Zcash developers will vote on whether to move forward with NU7 mainnet activation and lock in the activation height. NU7 is tentatively slated for November 5, cutting block time from 75 to 25 seconds and introducing a fee-removal mechanism. ZEC last traded at $1,076.53 on RISEx.
BTC spot ETFs are still seeing net redemptions, just at a slower clip. From Oct. 12-16, they logged roughly $228.4M in net outflows. Thursday alone shed $82.4M (IBIT -$71.8M, FBTC -$10.6M), wiping out the prior day’s modest inflow, while Tuesday saw a heavier $261.4M exit. That’s an improvement from the previous week’s $678.9M in BTC outflows and $542.2M in ETH outflows but flows remain firmly negative. BTC is trading around $81,066 on RISEx, with ETH near $2,365.
Day by day
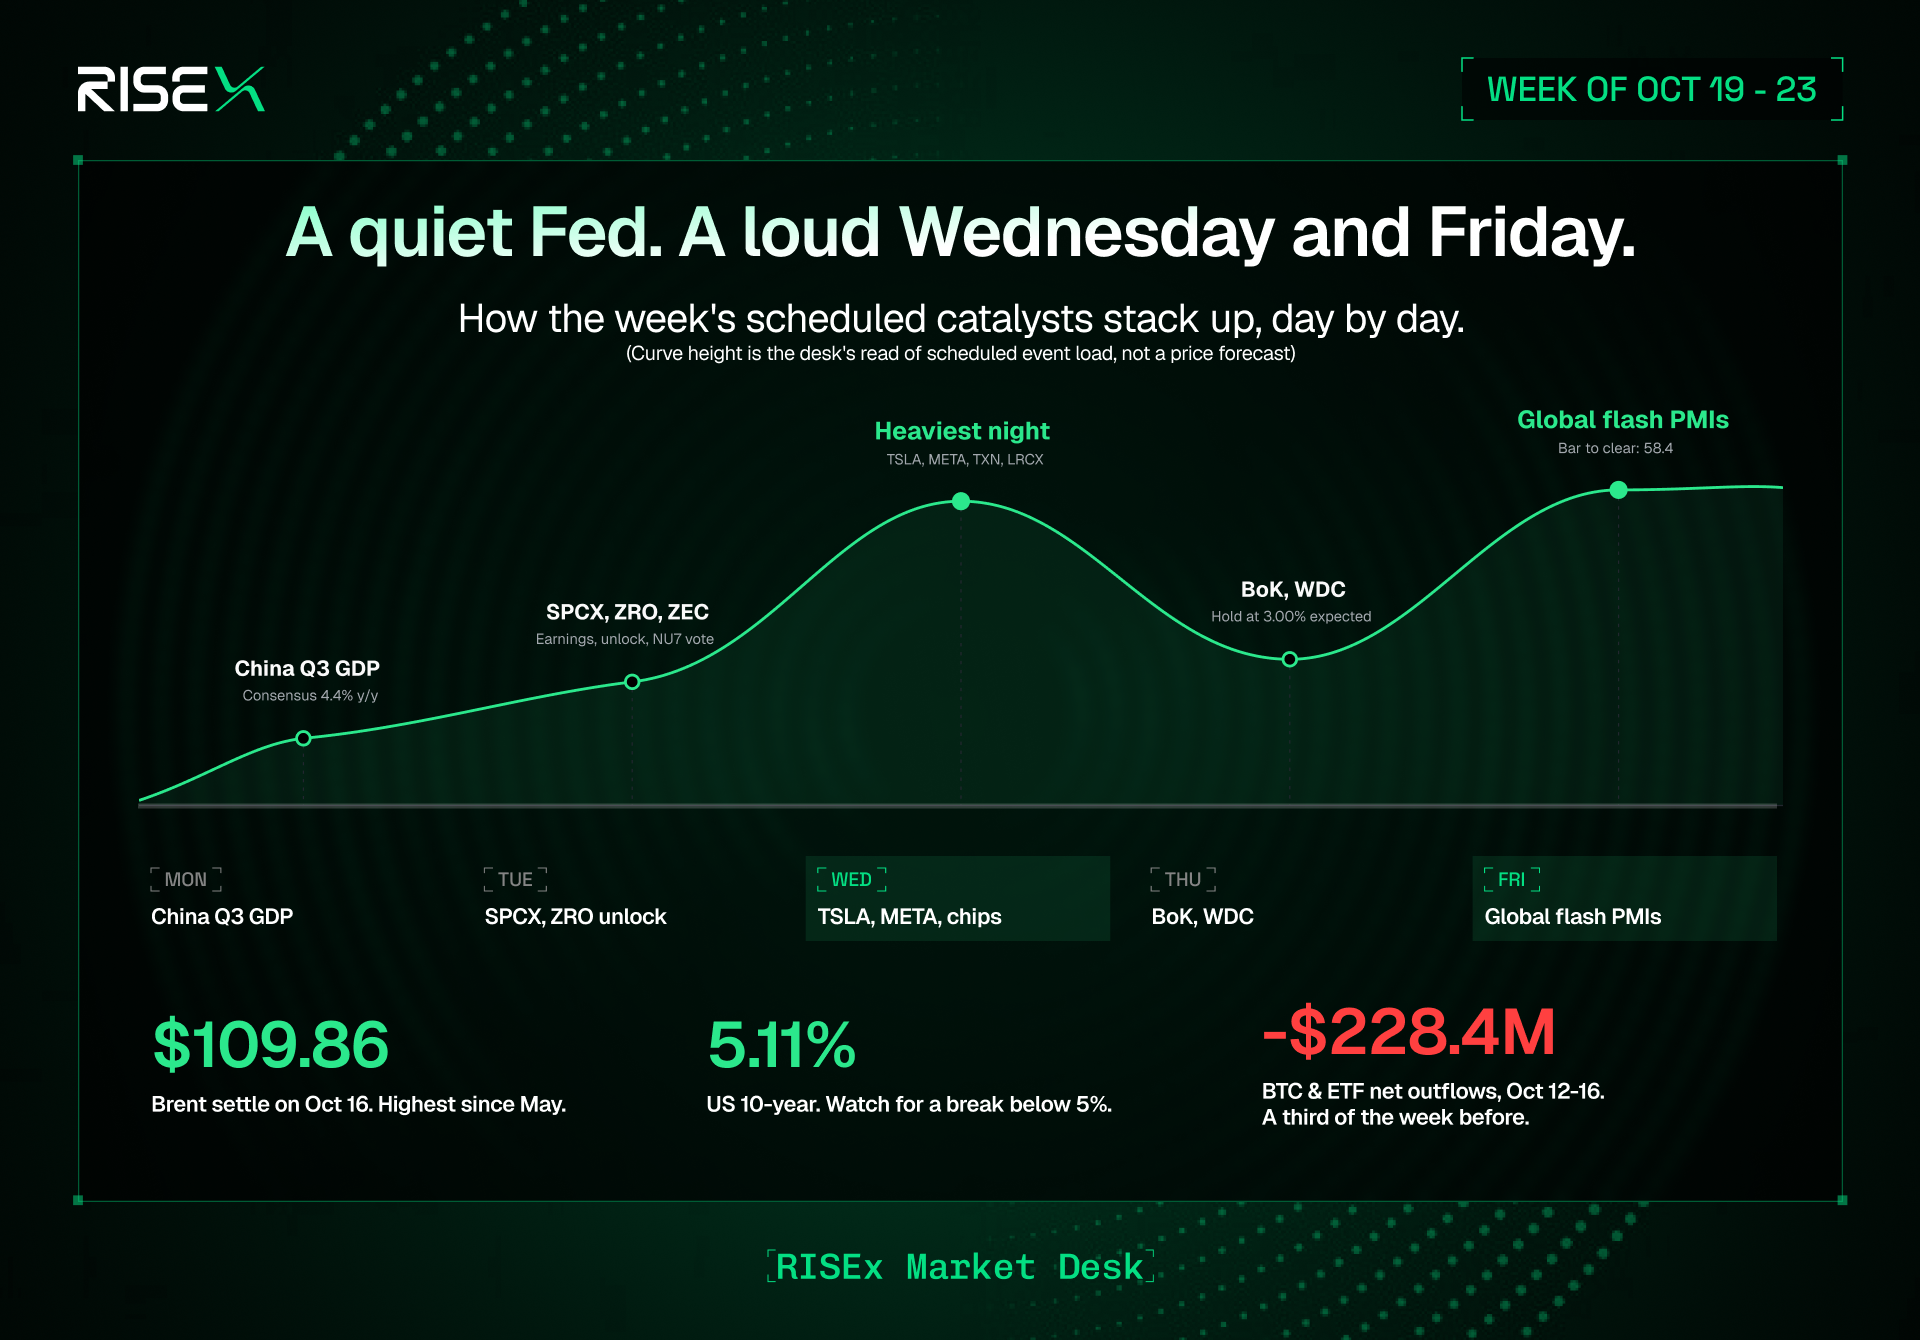
- Monday, October 19: China Q3 GDP and September activity data, consensus 4.4% year over year. Canadian CPI also prints, and ECB speakers Lane and Elderson are scheduled.
- Tuesday, October 20: SpaceX Q3 results, webcast at 4:30pm ET. The ZRO unlock of roughly 23.63M tokens and Zcash's NU7 activation decision.
- Wednesday, October 21: The week's heaviest earnings night. Tesla reports with its call at 5:30pm ET. Meta releases at 4:01pm ET with a call at 4:30pm ET, and Texas Instruments and Lam Research report the same night. UK CPI and several ECB speakers, including Lagarde, are also scheduled.
- Thursday, October 22: The Bank of Korea decides, with a hold at 3.00% expected. Western Digital reports fiscal Q1 2027 with a 4:30pm ET call. US weekly jobless claims also print.
- Friday, October 23: the biggest scheduled data point. Global October flash PMIs, with Japanese CPI and UK and Canadian retail sales alongside. Friday's options expiry is the standard weekly one.
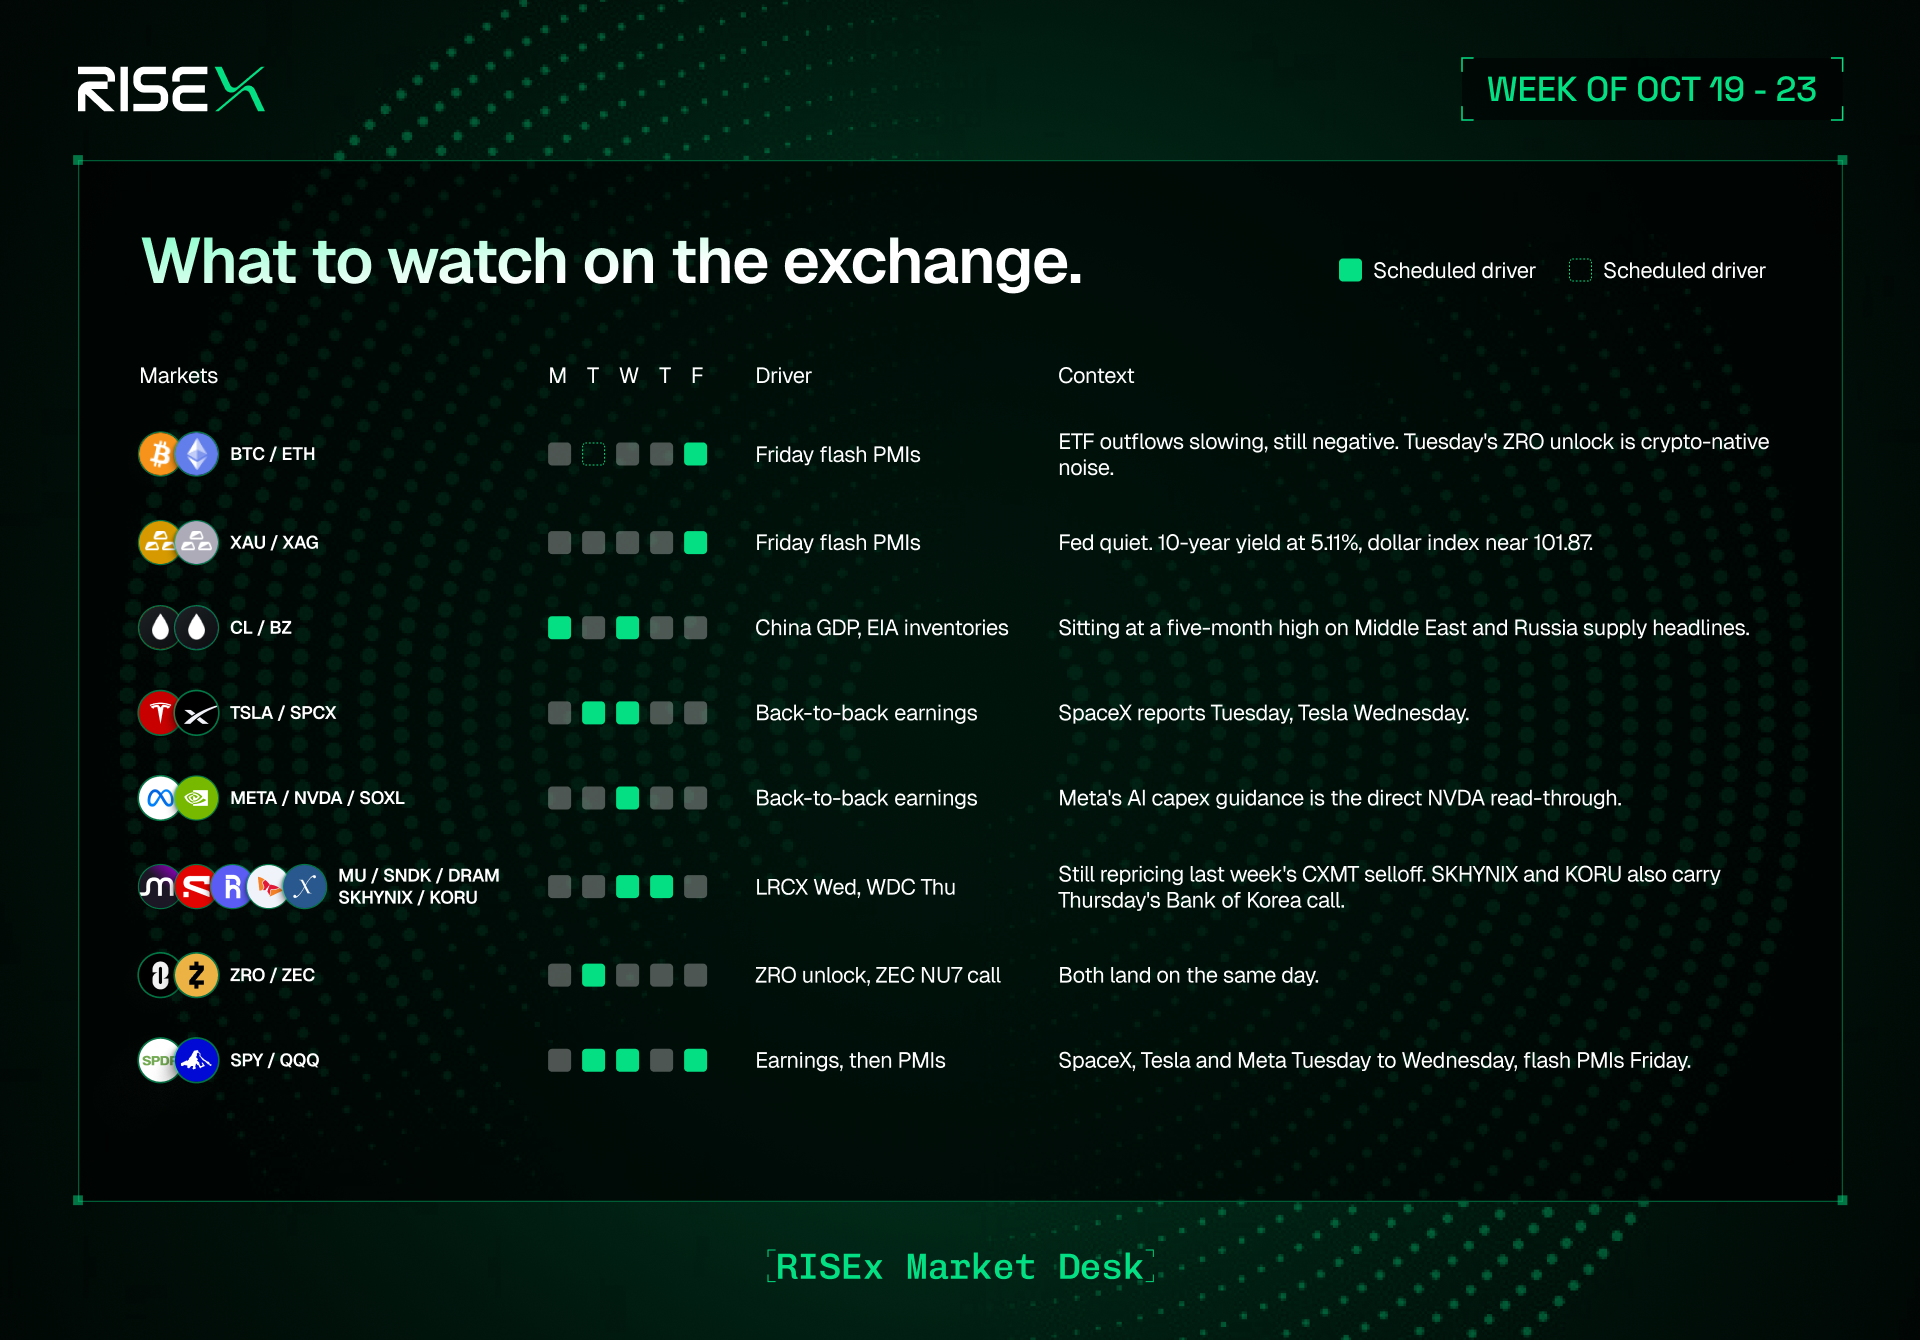
What to watch on the exchange
FAQ
Is there a Fed meeting this week?
No. The FOMC meets October 27 and 28, and Chair Warsh said on October 14 that the Fed is not in the business of hinting at policy ahead of time, so no scheduled Fed commentary is expected this week.
What are the odds of a Fed hike on October 28?
Roughly 10% to 16%, down from 40% to 60% right after the September CPI report. The same source has a December hike priced near 89%.
Which companies report earnings this week?
SpaceX on Tuesday, Tesla, Meta, Texas Instruments and Lam Research on Wednesday, and Western Digital on Thursday.
Why did memory stocks fall last week?
News that China's CXMT is advancing a 4F2 DRAM design sent SK hynix down roughly 18%, SanDisk roughly 15% and Micron roughly 13% on the week to October 16, even though Goldman Sachs called the fears overdone.
What is the biggest scheduled data point this week?
The global October flash PMIs on Friday, October 23. The baseline is September's final US composite PMI of 58.4.
Is Friday a monthly options expiry?
No. The monthly expiry already happened on October 16, so Friday carries only the standard weekly expiry.